 ALLIED
Before you change the property, understand it.
The Private Risk Profile is the document an Allied advisor works from all year. It is not an inspection report and not a proposal. It is an ordered understanding of one estate.
Four views of one estate.
What exists within the critical first five feet.
Vegetation, slopes, landscape, attachments, and surrounding fuels.
Conditions beyond the property line that may influence exposure.
How the family, estate team, and property are prepared when conditions change.
Then we establish priorities.
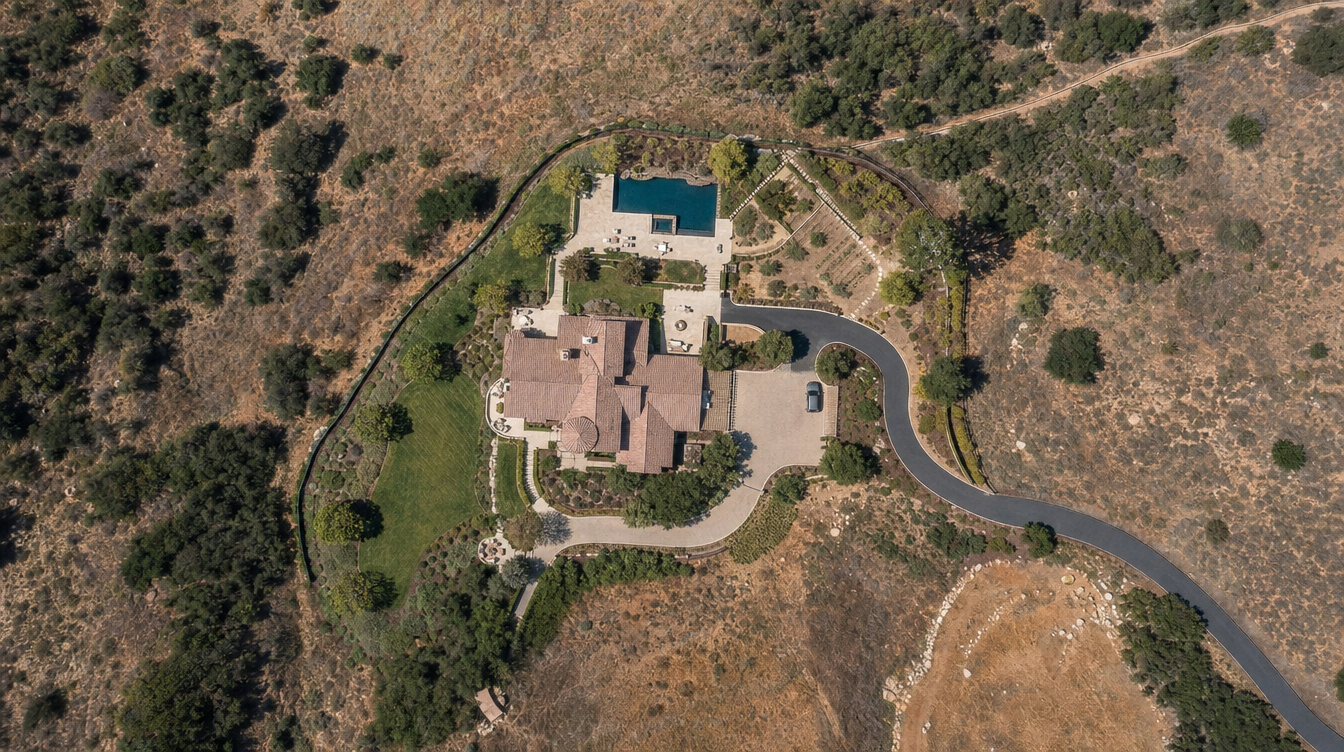
Four views, one property, assessed together.
Risk Profile
A private-client report, not a contractor estimate.
Every Client Family relationship produces one. It is written to be read by the family, the estate manager, and, where authorized, the insurance advisor. It is designed to be kept, revisited, and updated rather than filed once and forgotten.
The entire property. Understood at a glance.
The first pages give an executive-level view of the estate. They do not open with dozens of defects.
Executive advisory
Our preliminary assessment identified several correctable vulnerabilities that could increase the property’s susceptibility to ember-driven ignition. The highest priorities involve immediate structure-adjacent conditions, selected ember-entry points, and combustible landscape elements.
The property also contains several existing resilience features that should be maintained.
Address the highest-priority ignition pathways first, then establish an ongoing property resilience and seasonal preparedness strategy.
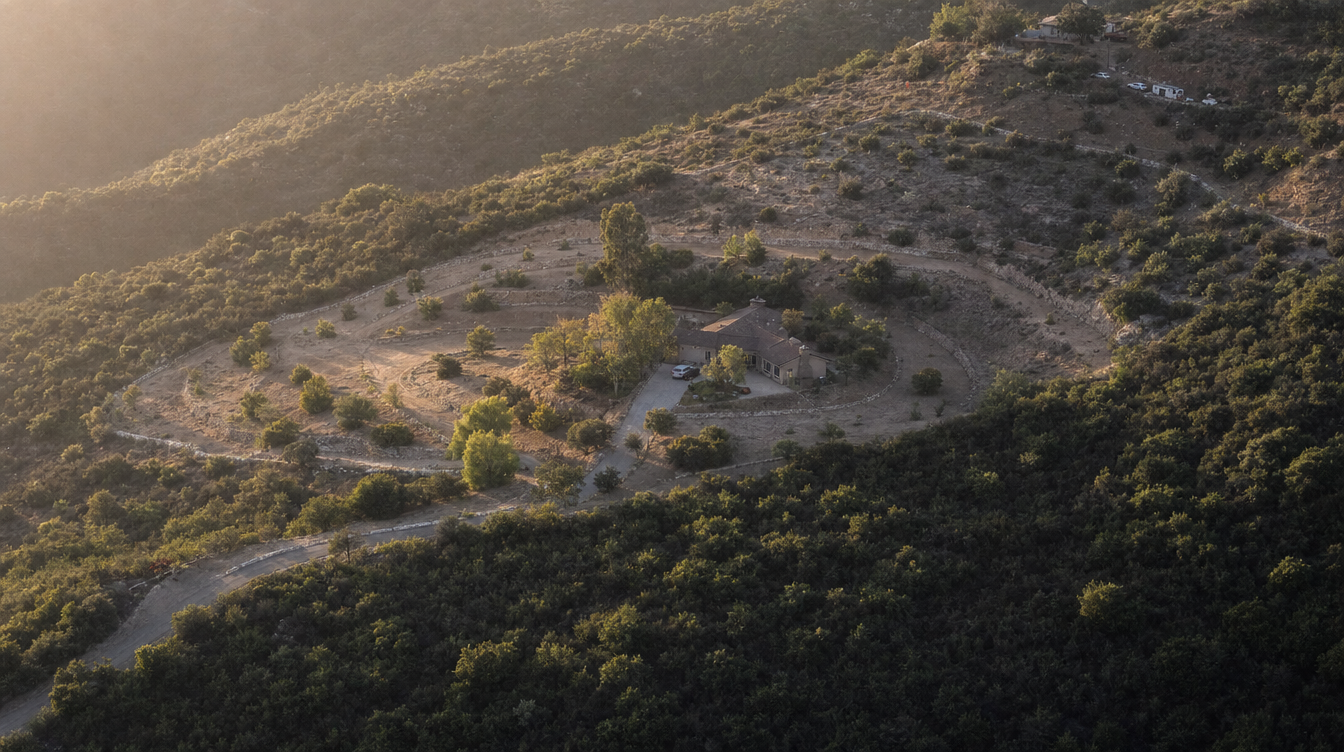
The entire property, understood at a glance.
How wildfire could reach this estate.
Every recommendation connects to a pathway.
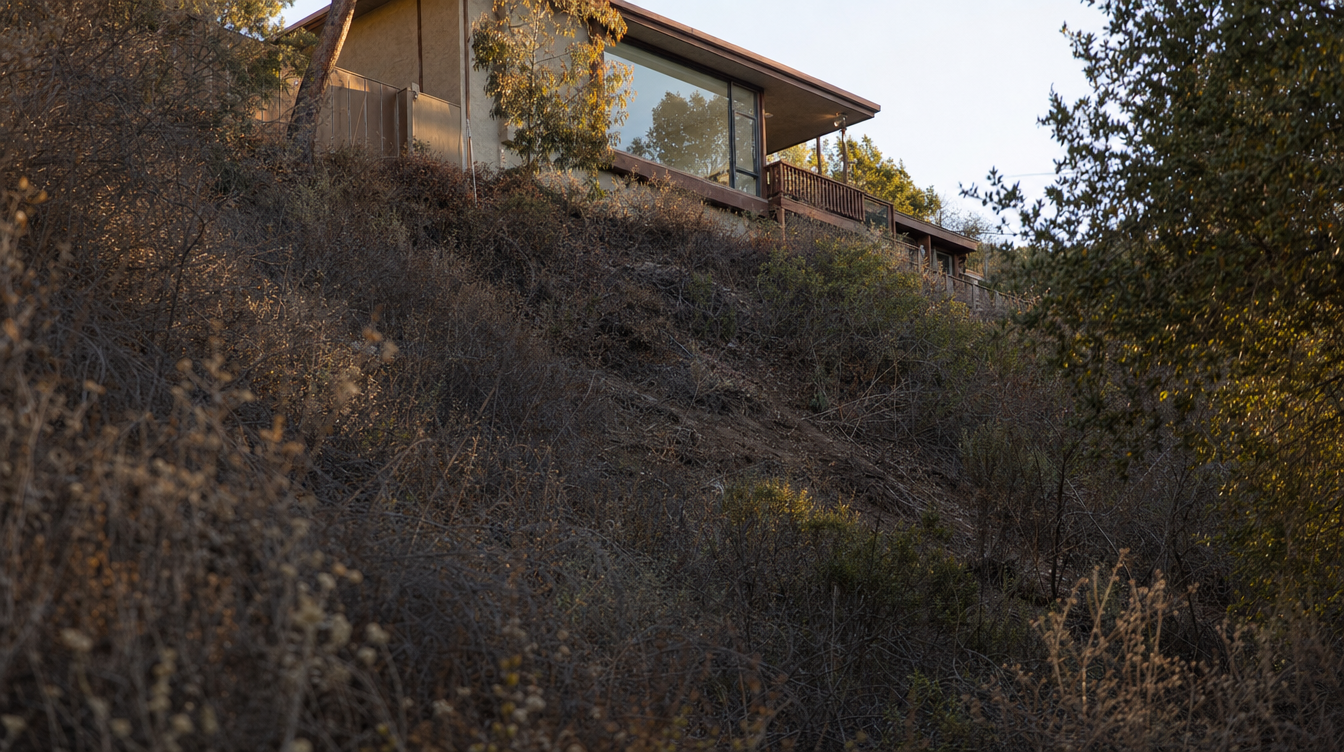
Continuous fuel up a slope is a pathway, not a view.
Wind-driven embers
Embers can travel significant distances ahead of the primary fire front.
Zone Zero
Combustible material immediately adjacent to the structure can create ignition pathways.
Structure
Certain construction materials and architectural details can influence wildfire vulnerability.
Surrounding fuels
Vegetation, slopes, neighboring properties, and terrain may influence how wildfire approaches the estate.
Not every vulnerability deserves immediate attention.
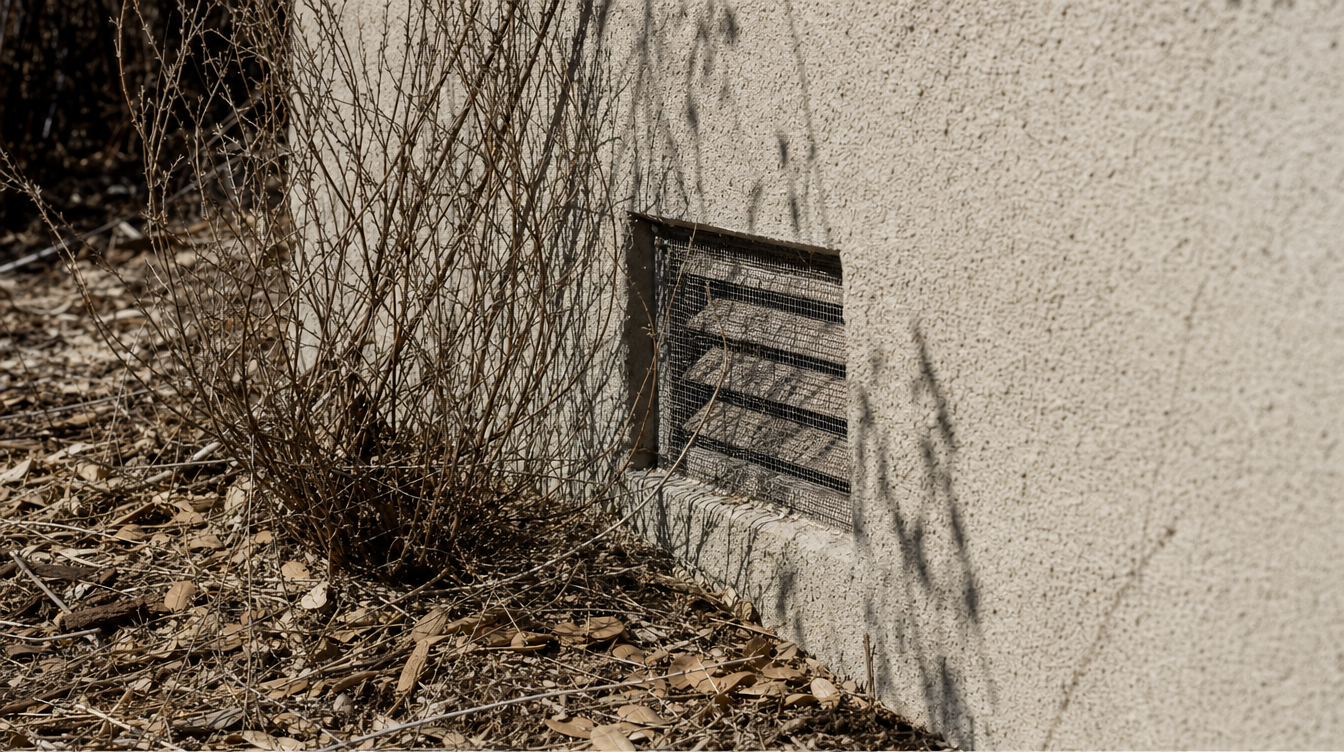
Priority I conditions sit within the first five feet.
This is where judgment shows. Recommendations are organized into four bands.
Conditions that may represent significant ignition vulnerabilities or relatively high-value mitigation opportunities.
- Ember-entry vulnerabilities
- Combustibles immediately adjacent to structure
- High-risk vent conditions
- Selected roof and gutter conditions
Important resilience improvements that should be incorporated into the property’s protection strategy.
- Selected landscape changes
- Fence transitions
- Deck improvements
- Window or siding considerations
- Secondary vegetation work
Conditions that do not currently warrant immediate intervention but should remain part of annual property review.
- Tree growth
- Neighboring vegetation
- Material aging
- Landscape changes
- Property modifications
Operational considerations that become important as wildfire conditions increase.
- Seasonal readiness
- Household responsibilities
- Estate manager protocols
- Water resources
- Evacuation considerations
- Prep & Go suitability
We tell you what not to spend money on.
Not every theoretical vulnerability deserves a project, and not every wildfire recommendation creates equal value. Our role is not to generate the longest possible construction list.
- What should happen now.
- What can wait.
- What should simply be monitored.
- And what may not justify the investment at all.
Good advisory sometimes means recommending that nothing be done. That is the difference between selling projects and providing stewardship.
See risk spatially.
Zones, fuels, slope, access, and water rendered as property intelligence rather than pins on a map.
Schematic. The plan produced for a Client Family is drawn to the actual parcel.
Evidence, not opinions.
Every significant finding is recorded the same way, so the profile becomes an ongoing property record rather than a one-time inspection.
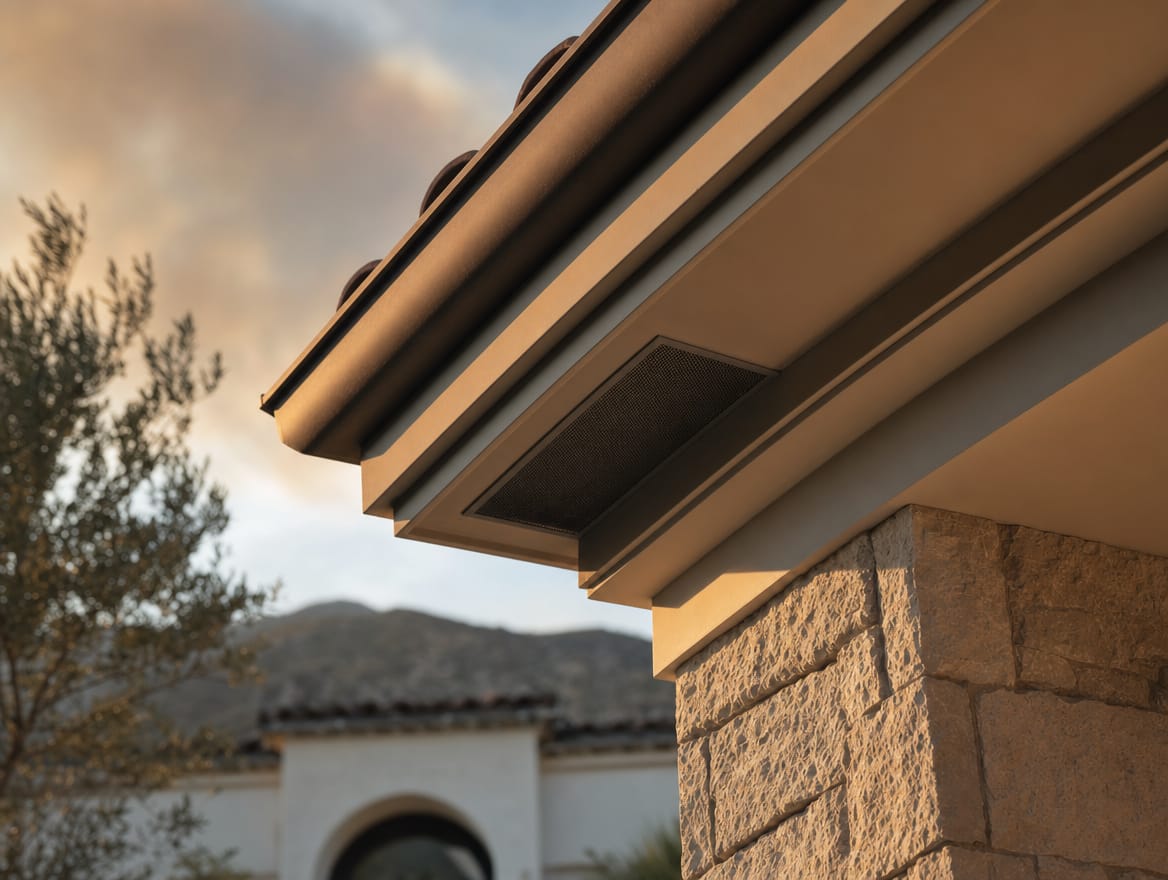
Status moves through Open, Planned, Completed, and Verified as work is carried out, which is what turns the profile into a record rather than a snapshot.
Resilience deserves documentation too.
The report should answer two questions, not one. Where are we vulnerable, and what have we already done well? The second becomes especially valuable in conversations with advisors and insurers.
- ✓Class A roof
- ✓Ember-resistant venting in selected locations
- ✓Appropriate vegetation clearance in portions of Zone Zero
- ✓Noncombustible hardscape
- ✓Accessible driveway
- ✓Maintained vegetation
- ✓Available water resources
Turn intelligence into action.
So nobody receives a forty-item report and wonders what to actually do Monday morning.
Make the work visible.
With Client Family authorization, appropriate portions of the Private Risk Profile may help support conversations with private client insurance brokers, underwriters, estate managers, family offices, property managers, and other authorized advisors.
Documentation may include existing property conditions, completed mitigation measures, before-and-after photographs, updated construction information, property resilience features, and annual review history.
Allied does not determine insurance eligibility, pricing, or underwriting outcomes. Our role is to help ensure meaningful property improvements are professionally documented.
Your estate changes. Your risk profile should too.
- Landscaping grows.
- Properties are remodeled.
- Roofs age.
- Neighbors change vegetation.
- New wildfire science emerges.
- Building standards evolve.
- Insurance requirements change.
Each review documents what changed, what was completed, what remains, and what should happen next.
Over time, Allied develops something extremely valuable: institutional knowledge of your estate.
What level of stewardship does this property require?
At the conclusion of the assessment, Allied recommends an appropriate Client Family relationship. The homeowner does not choose it.
The property demonstrates manageable structural exposure but requires ongoing landscape oversight, seasonal preparedness, advisor coordination, and documented mitigation.
Active-response capability should be reconsidered following completion of Priority I recommendations.
See what we see.
Before deciding what to change about your property, understand where the greatest vulnerabilities actually exist.
Qualified properties may be invited to complete an on-site Private Risk Assessment with Allied.
Better decisions begin with better intelligence.
You have invested significantly in the property. Before investing in its protection, understand what actually deserves your attention.